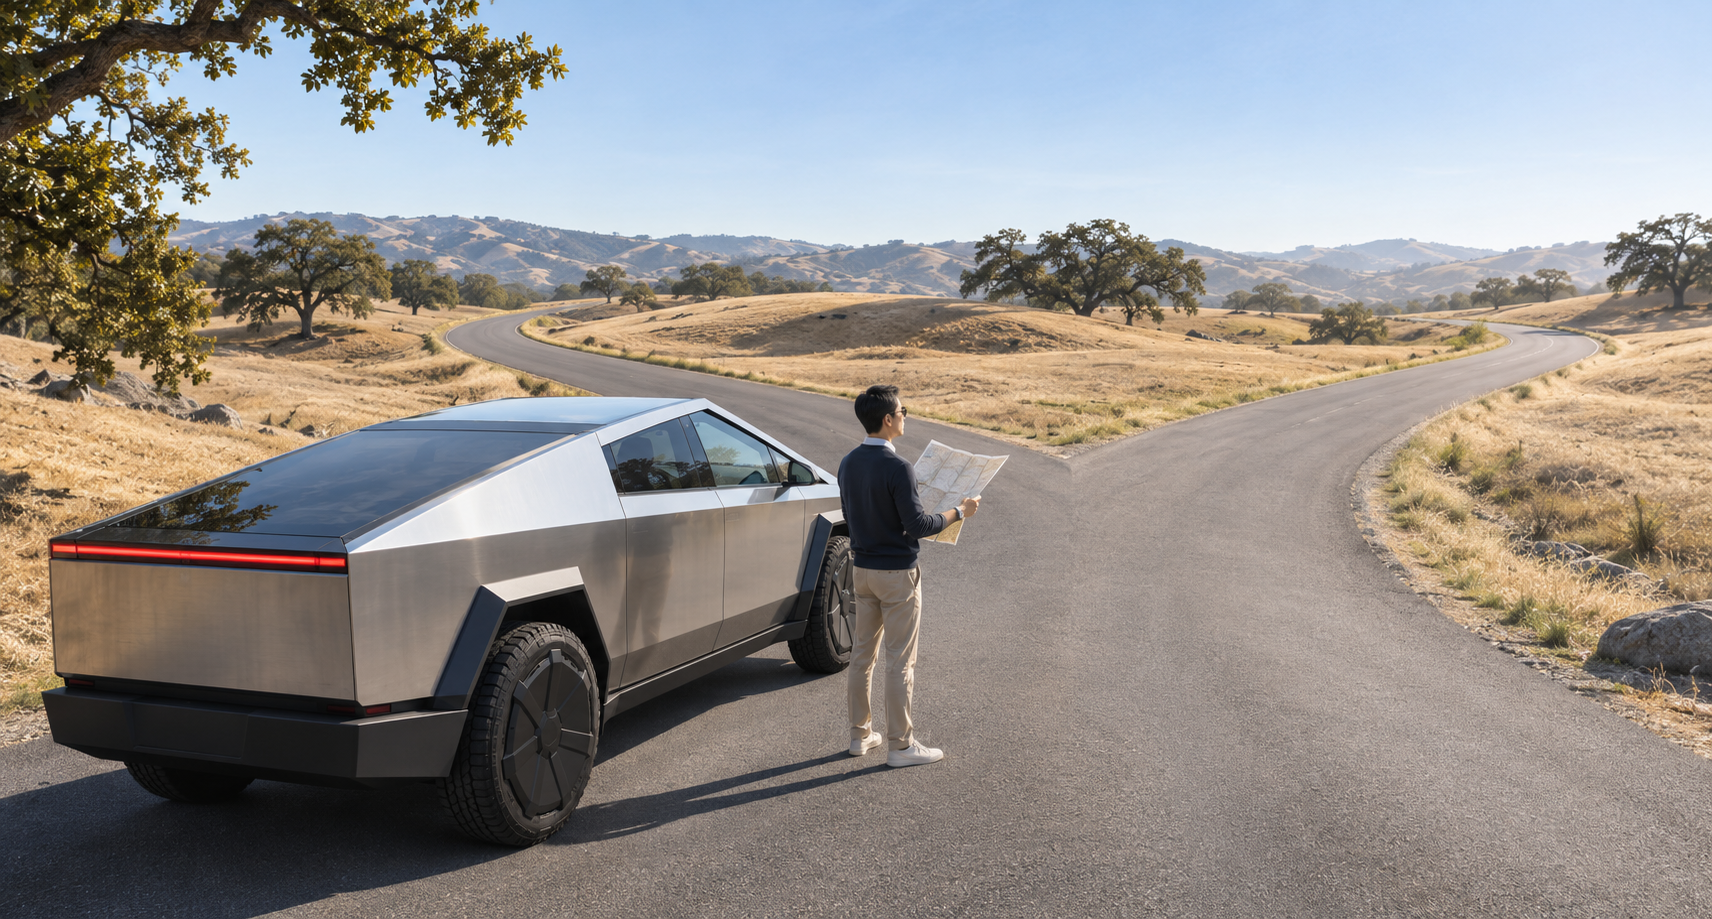
For a vehicle designed to attract attention, Tesla’s Cybertruck offers an interesting question: what happens when the headlines move on? Its angular body, unconventional engineering and ambitious sales expectations made it one of the most recognisable product launches in the automotive industry.
Following Elon Musk’s reported decision to wind down production and shift attention towards the Cybercab, investors have a different issue to consider. How should they assess the decision to stop backing a product that once carried such expectations?
Continuing with a disappointing project can waste resources, but abandoning one too early can sacrifice value that has yet to emerge. Management must weigh the evidence against the cost of further investment, often while defending decisions made years earlier. Investors face a similar difficulty when deciding whether to retain a struggling holding.
The next investment needs its own justification
After years of development, factory investment and public statements about a product’s potential, withdrawing support can be difficult. Closing a programme makes the disappointment visible, while continuing preserves the possibility of recovery. Neither consideration establishes whether the next commitment of capital is justified.
Cybertruck illustrates the gap that can develop between ambition and commercial delivery. Musk had predicted annual sales of 250,000 vehicles; figures from Cox Automotive put sales below 12,000 during the first nine months of 2026. Those periods are not directly comparable, but the difference in scale is substantial.
Weak sales alone do not establish the right response. Management still needs to assess achievable demand, production costs, future pricing and the expenditure required to improve the product.
The question is whether the expected return on further investment justifies its cost. Past expenditure matters where it has created assets or capabilities that remain useful. It cannot justify continuing simply because admitting defeat would be uncomfortable.
A setback can carry useful information
Manufacturing problems, poor distribution or an unsuitable launch price can undermine a new product without destroying its longer-term prospects. Further investment may be warranted where management can identify the obstacle, demonstrate a credible remedy and establish that the prospective economics remain attractive.
What matters is whether new evidence improves the investment case or merely provides another reason to extend the deadline for proving it.
Pharmaceutical development makes this distinction particularly clear. A disappointing study might provide evidence supporting investigation of a different dose or patient population. Alternatively, it could undermine the biological rationale on which the programme depends. Pursuing a revised approach requires supporting data; the possibility of a different outcome is insufficient justification on its own.
Investors should ask whether the probability of success has changed and how much reaching the next meaningful milestone will cost. Would the project still receive funding on today’s information if it were being considered for the first time? That question helps separate a fresh investment judgement from a defence of an earlier decision.
Decide what would change the decision
A vehicle programme gives management several ways to test progress: demand at a commercially viable price, manufacturing costs, warranty claims and the expenditure needed to reach sustainable production. Tracking those measures against agreed expectations makes it harder to explain away every disappointment as a temporary setback.
Milestones should inform judgement rather than operate as automatic switches. Missing a deadline because a useful technical improvement takes longer is different from missing it because the underlying assumptions no longer hold.
Shareholders can look for consistency between management’s explanations and subsequent decisions, including whether targets change without a convincing commercial reason. For investors reviewing their own holdings, the same approach provides a useful check: a thesis becomes difficult to test when every adverse development is described as temporary and every favourable development as confirmation.
A failed product may leave valuable assets
Although a discontinued product may never recover its development costs, some of the work behind it can remain commercially useful. Engineering knowledge, battery technology, manufacturing processes and supplier relationships may support other projects. Cybertruck’s electrical and mechanical development could therefore retain value even if the vehicle falls short of its original ambitions.
That potential needs careful treatment in a valuation. Transferable technology should be assessed through the future expenditure it avoids or the earnings it can help generate. Its existence does not establish that the original programme earned an adequate return.
When valuing the replacement project, investors should establish whether its forecasts already incorporate the benefits of inherited technology. Adding a separate value for that technology could count the same economic benefit twice.
The replacement project must earn its funding
Redirecting resources towards Cybercab would introduce a different set of commercial, technological and regulatory requirements. Its prospects need assessing independently of the decision to reduce Cybertruck production. The case for ending one commitment may be strong even when the best destination for the released resources remains uncertain.
An investor selling a disappointing holding faces a comparable decision. Releasing capital does not make the next purchase attractive; its expected return, valuation and contribution to portfolio risk still need examination.
Without that reassessment, capital can move from one persuasive story to another while the underlying decision process remains unchanged.
A winning investment is more than a rising price
The familiar instruction to “cut your losers and run your winners” leaves considerable room for interpretation. A falling share price can accompany a deteriorating business, an excessive starting valuation or a temporary change in market sentiment. Rising prices may reflect improving prospects while also leaving less room for future disappointment.
The purchase price remains relevant to the investor’s realised return and tax position. It should not determine whether a holding deserves its place today.
For management and shareholders alike, future returns need reassessing as the evidence changes. Persistence earns its justification through credible economics and measurable progress. Deciding to stop requires equally careful analysis, particularly when the conclusion conflicts with years of investment and public conviction.